A credit bureau error can tank your score without warning, costing you thousands in higher interest rates or denied loans. These mistakes happen more often than you’d think-and most people never catch them.
This credit bureau errors guide walks you through spotting inaccuracies, challenging them directly, and getting them removed from your report. We at Bontrager Law help people fight back against reporting mistakes every day, and we’ve seen firsthand how quickly errors can be fixed when you know the right steps.
How Credit Bureau Errors Happen
Common Types of Reporting Mistakes
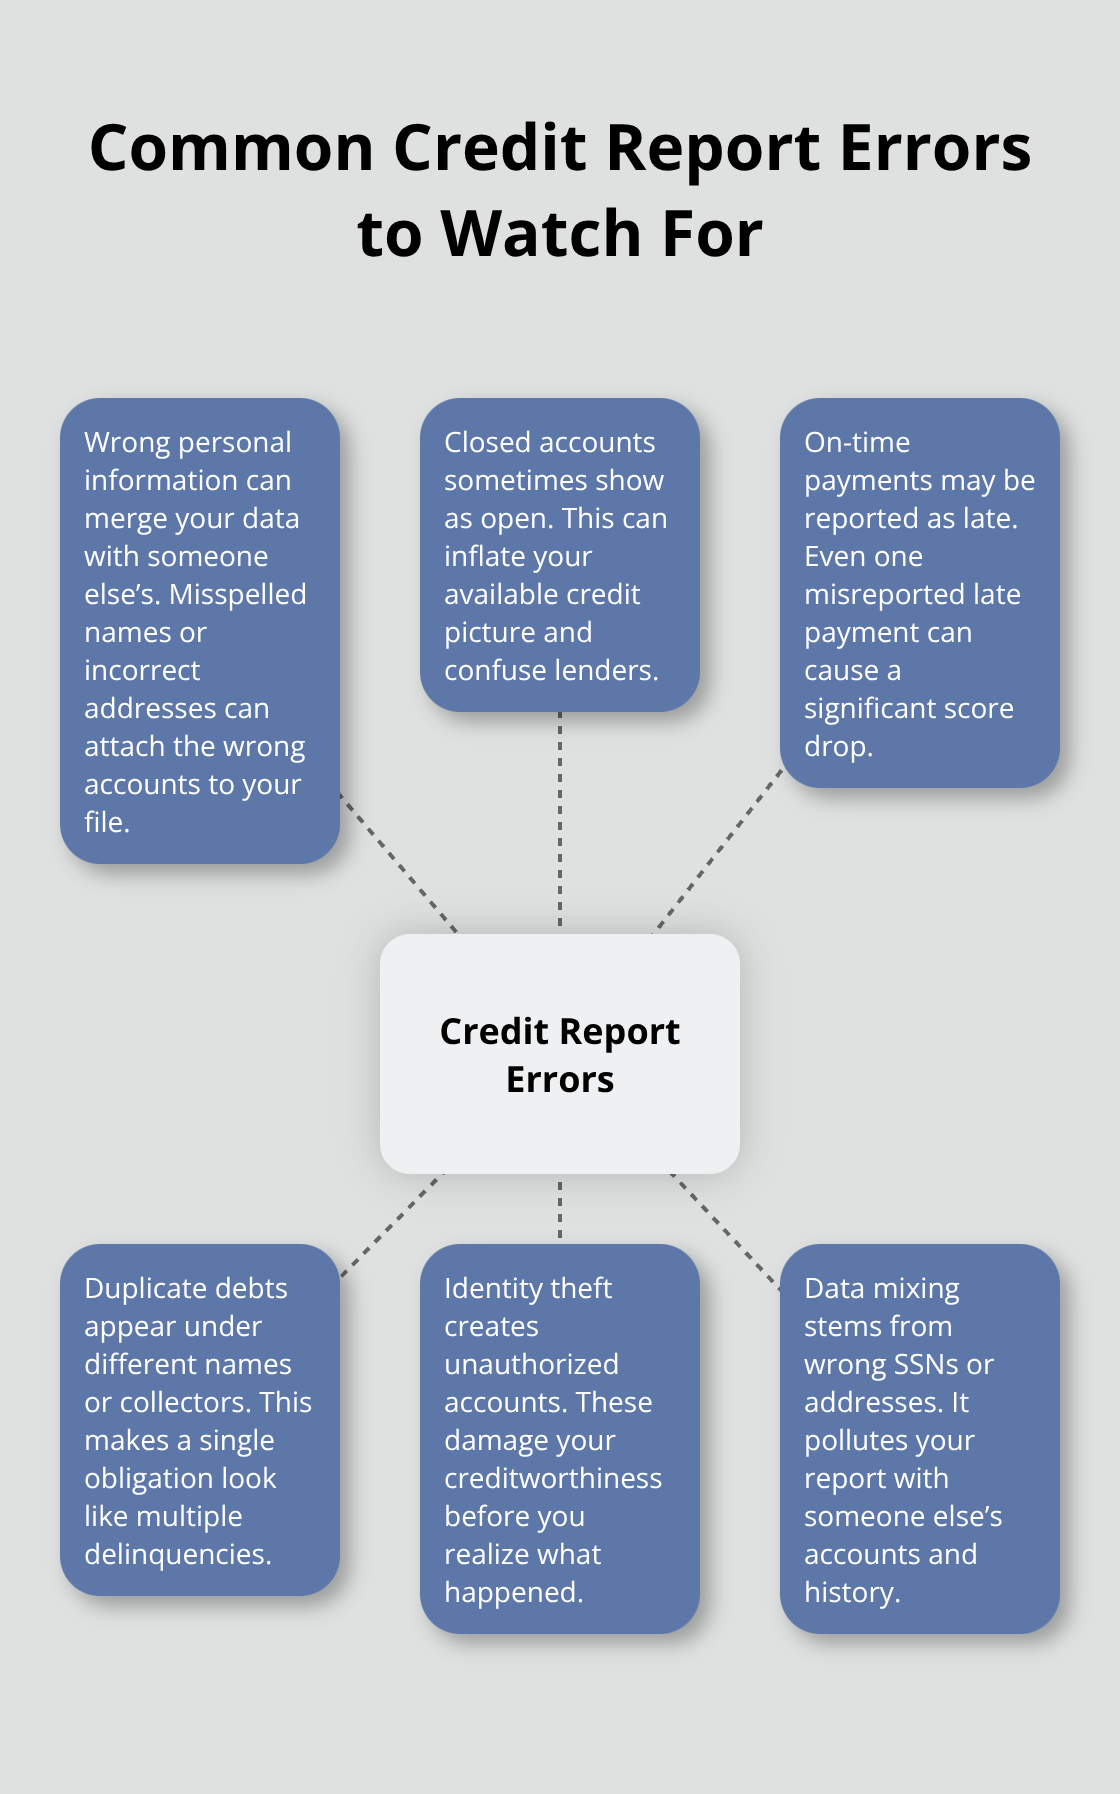
Credit reporting errors stem from broken systems rather than malice. Equifax, Experian, and TransUnion receive millions of data updates daily from banks, credit card companies, landlords, and debt collectors. When a creditor reports information late, incorrectly formats an account number, or fails to update a payment status, the error flows directly onto your report. The CFPB found that common mistakes include wrong personal information like misspelled names or incorrect addresses that can merge your accounts with someone else’s, accounts showing as open when they’re closed, payments marked late when they were on time, and duplicate listings of the same debt under different names or collectors.
Why Creditors and Bureaus Make Mistakes
Creditors make mistakes when they misprocess payments, fail to update account status after you pay off a balance, or report to only one bureau instead of all three, creating inconsistencies across your files. Data entry errors happen constantly-a transposed digit in an account number, a missed decimal point in a balance, or confusion about whether you’re an authorized user or the primary account holder. The bureaus aren’t entirely passive either; they often accept data without verification, relying on creditors to police themselves. When volume is high and profit margins matter, accuracy takes a backseat.
The Real Impact on Your Credit Score and Finances
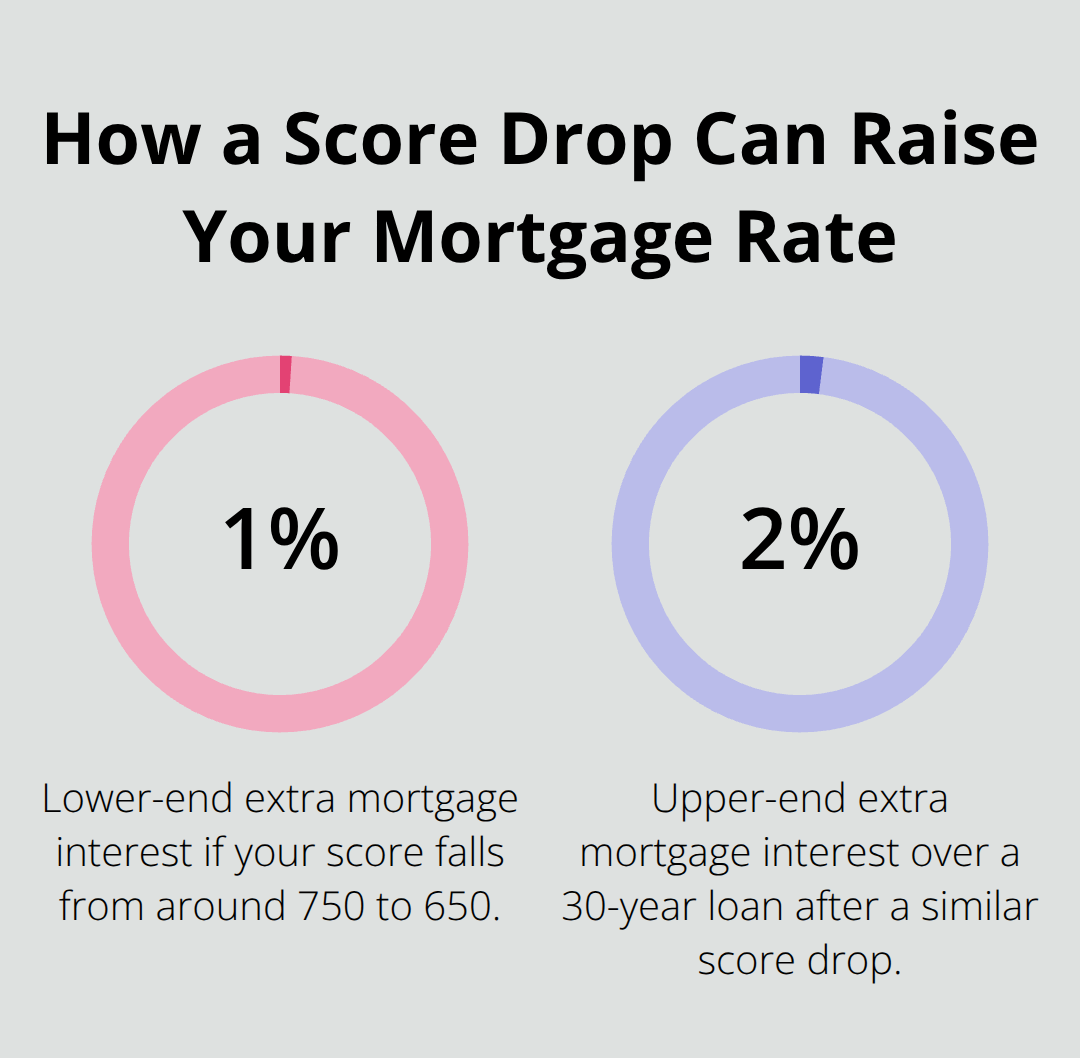
A single incorrect late payment can drop your score by 100 points or more, depending on your current score and payment history. According to the FTC, your credit score directly affects your borrowing ability, the interest rates lenders offer you, and increasingly influences hiring decisions, insurance premiums, and housing approvals. If a mistake tanks your score from 750 to 650, you might pay an extra 1-2% in mortgage interest over 30 years, costing tens of thousands of dollars.
An unauthorized account listed on your report signals identity theft and damages your creditworthiness before you even realize it’s there. High credit utilization ratios caused by incorrect balance reporting can suppress your score even if you pay on time. The CFPB data shows that consumers with errors on their reports face loan denials, higher insurance costs, and rental application rejections. Inaccurate information can legally remain on your report for seven years, and bankruptcy information for ten years (meaning every month an error sits uncorrected is a month your score suffers and lenders see false information about your reliability).
The sooner you identify and dispute an error, the sooner you can limit the damage. That’s why knowing how to spot these mistakes on your report matters more than most people realize.
How to Spot Errors on Your Credit Report
Get Your Free Reports and Review Them Strategically
Start by obtaining your free credit reports from all three bureaus-Equifax, Experian, and TransUnion-through AnnualCreditReport.com. The FTC lets you check each bureau’s report for free once per week through 2026, which means you can pull reports strategically throughout the year instead of burning through your annual allotment at once. This approach helps you catch errors faster and monitor changes over time without waiting a full year between reviews.
Scan for Identity Theft and Data Mixing
When you open your report, scan for accounts you don’t recognize, addresses where you’ve never lived, and employers you never worked for. These red flags signal identity theft or data mixing. Unfamiliar accounts on your file represent immediate threats to your creditworthiness and warrant urgent action. Check your personal information too-misspelled names, wrong Social Security numbers, or addresses linked to your file can cause your data to merge with someone else’s, creating a mess of false accounts on your report.
Look for Payment History and Balance Errors
Find any account marked late when you paid on time, closed accounts still showing as open, or duplicate listings of the same debt under different names or collection agencies. According to the CFPB, these mistakes rank among the most common errors that tank scores. The credit utilization ratio matters here as well. If your report shows a balance higher than what you actually owe or a credit limit lower than reality, your utilization percentage climbs and your score drops even if payments are accurate.
Document Everything and File Your Dispute
When you spot something wrong, write down the account number, the error, and why it’s wrong. Gather supporting documents-bank statements showing the payment, a canceled check, or your credit card statement proving the balance is incorrect. Send your dispute to the relevant bureau by certified mail with return receipt to create proof of delivery. The FTC provides a sample dispute letter template you can follow. You can also dispute online or by phone with Experian at 888-397-3742, TransUnion at 800-916-8800, or Equifax at 866-349-5191, though mail creates a better paper trail if the bureau drags its feet.
Track the Investigation and Verify Corrections
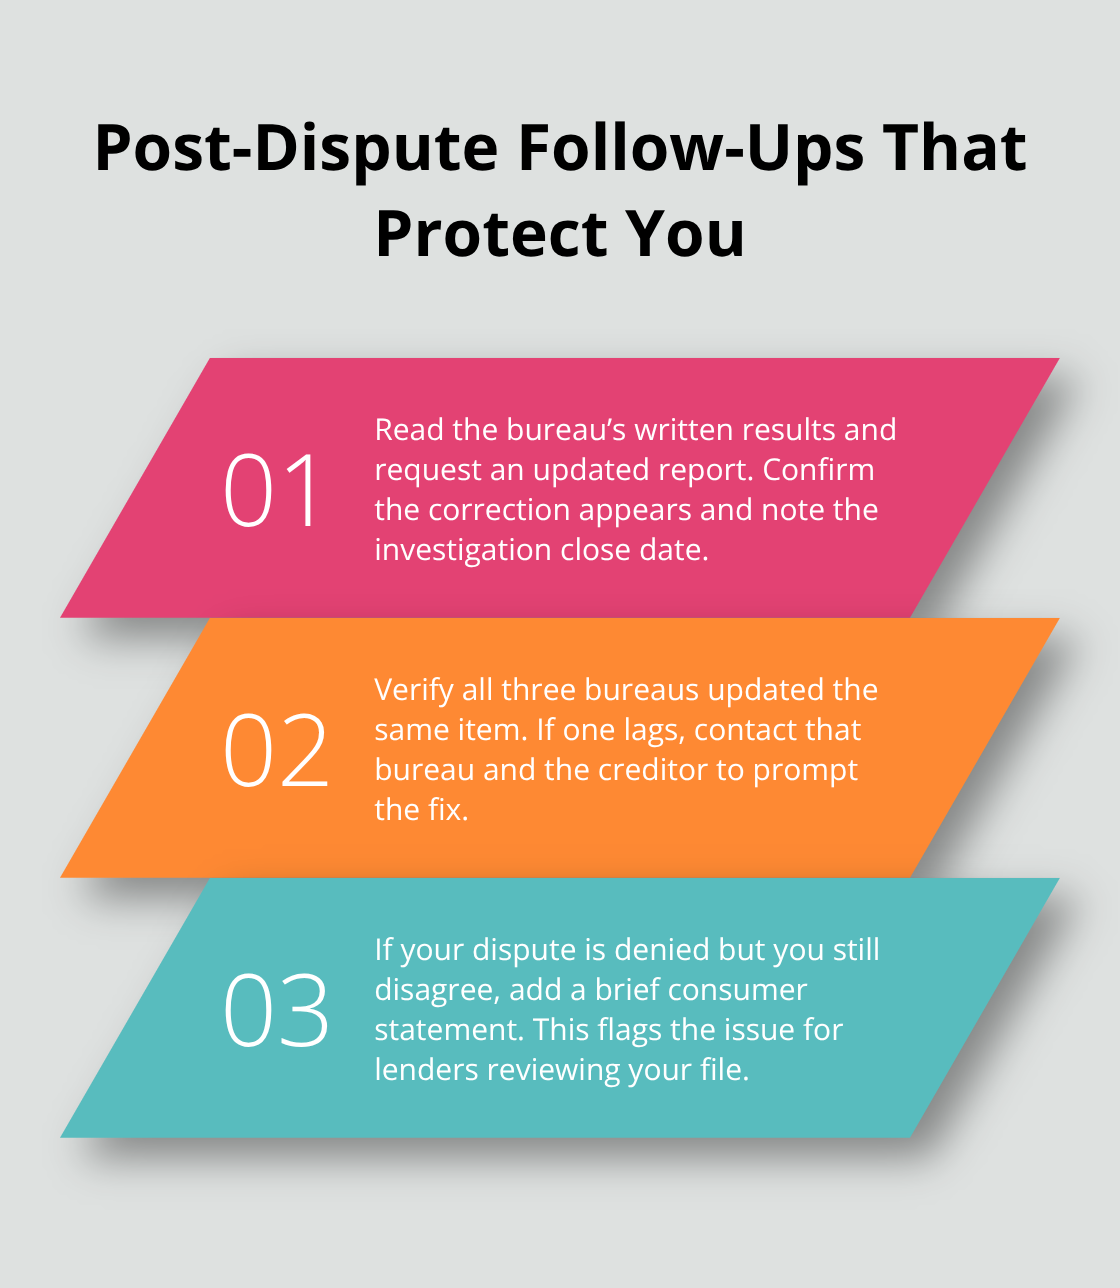
The bureau has 30 days to investigate and must forward your dispute to the creditor who reported the information. If the creditor confirms the error, all three bureaus update your file automatically. If they confirm the information is accurate but you still disagree, you can add a written statement to your report explaining your dispute. Monitor your reports after filing to confirm the correction took hold-sometimes bureaus miss updating one of the three files. Once you’ve filed your dispute and tracked the results, the next step involves understanding what happens when the creditor responds and how to escalate if the bureau’s investigation doesn’t resolve the problem.
How to Dispute and Correct Errors the Right Way
Submit Your Written Dispute to the Bureau
Filing a dispute with a credit bureau requires precision. The FTC mandates that bureaus investigate your claim within 30 days, but only if you submit it correctly. Send a written dispute to the bureau that reported the error-Equifax, Experian, or TransUnion. Include your full name, address, the specific account number, and a clear explanation of what’s wrong and why. Attach copies of supporting documents like bank statements, canceled checks, or credit card statements that prove the error. Send everything by certified mail with return receipt requested; this creates proof the bureau received your dispute and starts the 30-day clock.
You can also dispute online or by phone-Experian accepts disputes at 888-397-3742, TransUnion at 800-916-8800, and Equifax at 866-349-5191-but certified mail gives you a paper trail if the bureau ignores your claim or drags out the investigation. The FTC provides a sample dispute letter template you can follow to structure your message correctly.
Contact the Creditor Directly
The creditor who supplied the information must also receive your dispute. The bureau forwards your complaint to them during the investigation, but a separate letter directly to the creditor accelerates the process. Include the same documentation and explain why the information is inaccurate. If the creditor confirms the error exists, they must notify all three bureaus to correct their files. If they ignore you or confirm the information is accurate, you still have leverage-when you dispute an item with a bureau, that bureau must note on your report that you are disputing it, signaling to lenders that the information is contested.
Verify Corrections Across All Three Bureaus
After the 30-day investigation window closes, the bureau sends you written results. If the error is removed, request a free updated copy of your report to verify all three bureaus made the correction. Many people overlook this step and later discover one bureau failed to update. If the dispute is unsuccessful and you disagree with the outcome, add a written consumer statement to your file explaining your position; this statement appears on future reports you share with lenders.
Build Your Documentation File
Keep copies of all dispute letters, documents, and the certified mail receipts in a file folder-these records prove you acted diligently if you need to escalate the matter or file a complaint with the Consumer Financial Protection Bureau. This documentation becomes invaluable if disputes stall or if you need professional help to push back against a bureau or creditor that refuses to correct clear errors.
Conclusion
Finding a credit bureau error on your report demands immediate action. Pull all three reports from AnnualCreditReport.com, identify the mistake, gather your supporting documents, and file a written dispute with the bureau within days of discovery. Send copies to the creditor as well, since the 30-day investigation window starts the moment the bureau receives your complaint and certified mail with return receipt protects you by proving delivery.
Monitor your reports after the investigation closes to confirm the correction took hold across all three bureaus. If one bureau fails to update, contact them again and follow up with the creditor to verify they notified all three agencies. This credit bureau errors guide emphasizes speed and documentation because every month an error remains on your file costs you in lower scores and worse lending terms.
We at Bontrager Law understand how frustrating these disputes become when bureaus drag their feet or creditors refuse to acknowledge mistakes. If your dispute stalls, the bureau ignores your complaint, or you face retaliation from a creditor, contact us for a free case review to explore your options. Federal law gives you the power to challenge errors, demand corrections, and hold bureaus and creditors accountable.