Identity theft can destroy your financial life in weeks. Fraudsters open accounts in your name, rack up debt, and tank your credit score while you’re left cleaning up the mess.
We at Bontrager Law help California residents fight back against identity theft and restore their financial health. This guide walks you through the warning signs, immediate steps to take, and how legal action can hold thieves and creditors accountable.
How to Spot Identity Theft Before It Spirals
The moment you notice something wrong with your credit is the moment you act. Most people discover identity theft through their credit report, a denial letter, or a call from a debt collector about accounts they never opened. The Federal Trade Commission reported over 1.1 million identity theft complaints in 2022, and California residents made up a significant portion of those victims. Fraudsters operate for months before you catch on, racking up thousands in debt under your name.
Unfamiliar accounts signal immediate fraud
Pull your credit reports from Equifax, Experian, and TransUnion right now. Look for accounts you absolutely did not open. Thieves typically open credit cards, auto loans, or personal lines of credit because they generate cash quickly. Credit card fraud shows up as unfamiliar charges on your existing accounts, but new account fraud is far worse-the thief opens an entirely new credit line in your name and maxes it out before vanishing. You’ll see inquiries from lenders you never contacted. Promotional inquiries look similar to fraud inquiries but are harmless; real fraud shows hard inquiries from credit card companies and loan providers you don’t recognize. Each fraudulent account tanks your credit score and creates a paper trail of debt collectors coming after you.
Free credit reports give you ammunition to fight back
California victims with a police report obtain up to 12 free credit reports in the following 12 months from all three bureaus. This access gives you the ammunition to fight back and track fraudulent activity across your credit file. You can request detailed proof of your police report and identity when applying for these reports. Monitor these reports carefully for accounts you don’t recognize and for unfamiliar inquiries. The more documentation you gather, the stronger your case becomes against fraudsters and creditors.
Debt collectors calling about unknown debts demands immediate action
A call from a debt collector about a debt you don’t recognize signals criminal identity theft. Ignore it and you risk a judgment against your name, wage garnishment, and a criminal record if the thief committed crimes under your identity. Write to the collector in writing and dispute the debt under California Civil Code section 1798.93, attaching your police report and the Federal Trade Commission Identity Theft Affidavit. Collectors must stop collection efforts while investigating. The sooner you document everything, the sooner you shut down fraudulent accounts.
Once you identify the theft and contact collectors, you need to take control of your credit file itself-and that means placing protective measures that prevent new accounts from being opened in your name.
What Identity Theft Does to Your Credit and Finances
Your credit score collapses within weeks
Your credit score drops fast when identity theft hits. A single fraudulent credit card account can lower your score by 100 points or more, depending on the credit utilization and payment history the thief creates. Fraudsters typically open multiple accounts at once, and each new account generates a hard inquiry that tanks your score further. Within weeks, your credit profile transforms from solid to toxic.
Lenders see a file full of recent inquiries, maxed-out accounts, and missed payments you never made. Banks deny your mortgage application. Credit card companies reject your requests. You’re locked out of borrowing money for years, even after you’ve proven the fraud wasn’t your fault. The California Department of Justice notes that victims often face recovery times stretching 12 to 24 months just to stabilize their credit file, and that’s if you act immediately and aggressively.
Employment and housing opportunities vanish
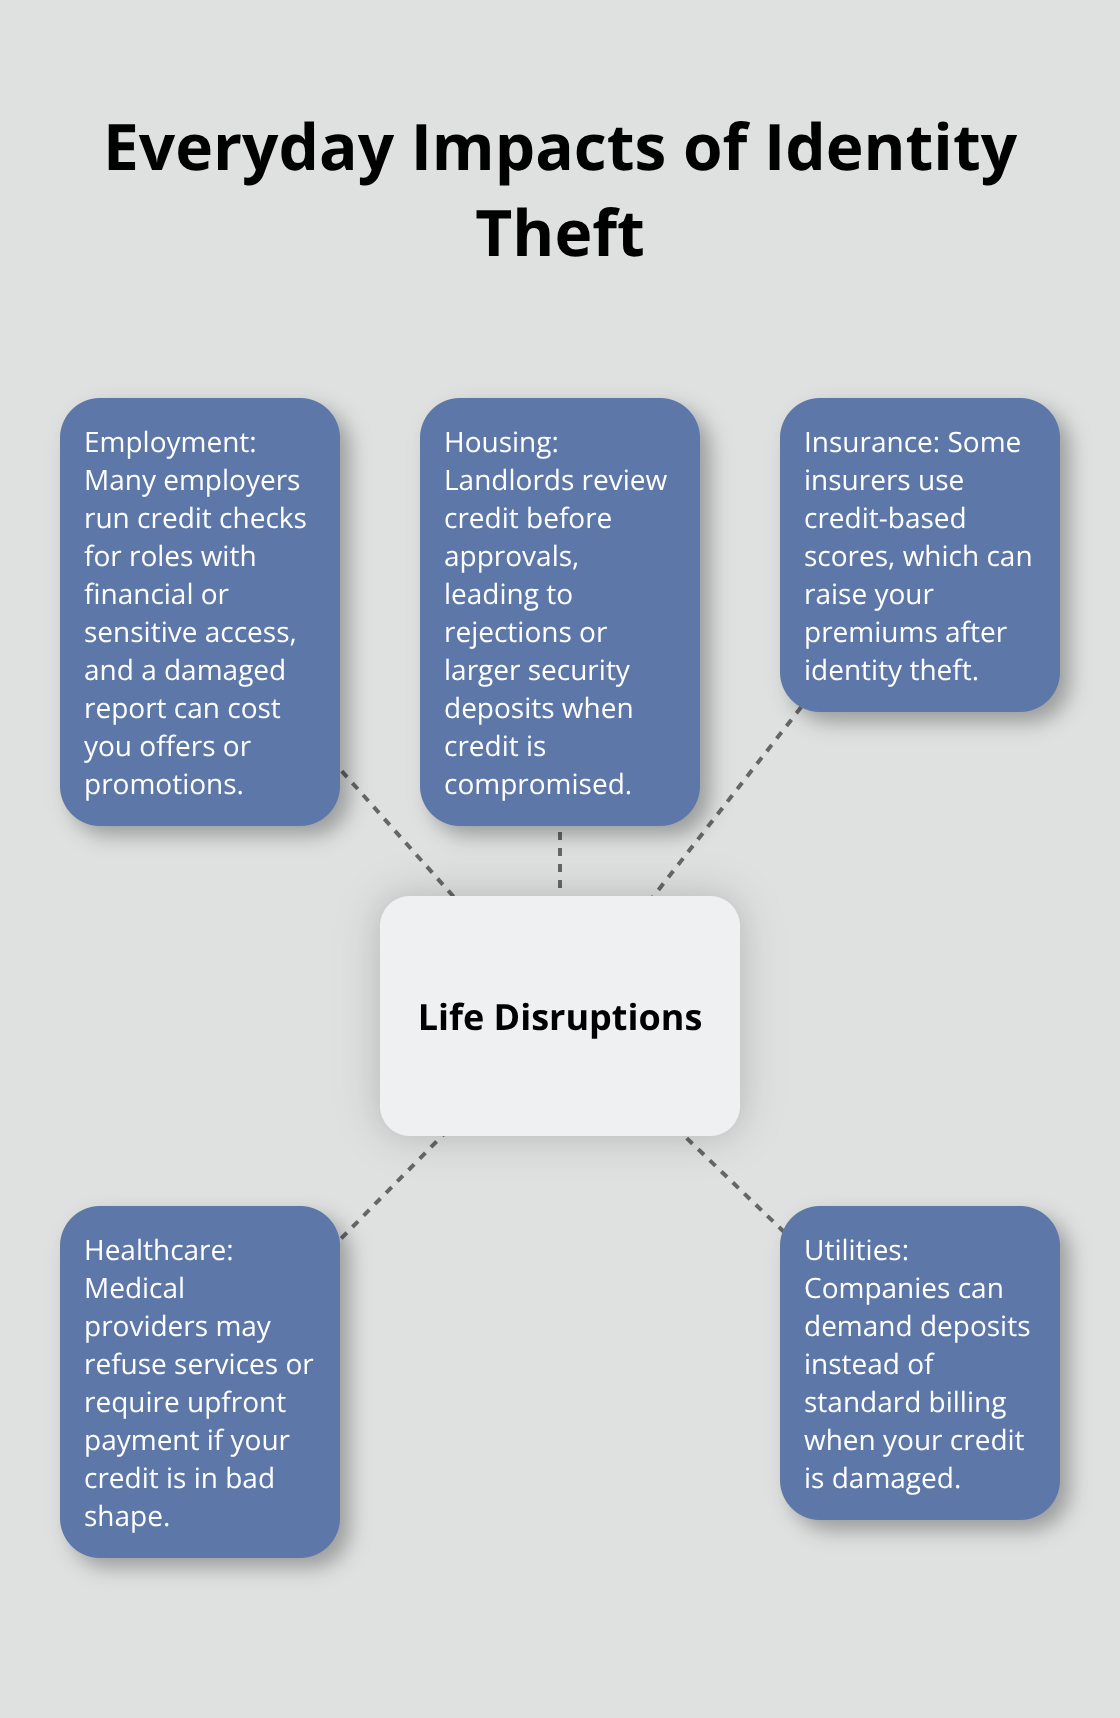
The financial fallout extends far beyond your credit score. Employers increasingly run credit checks on job candidates, particularly for positions involving financial responsibility or access to sensitive information. A compromised credit report can cost you a job offer or promotion you’ve already earned. Landlords pull credit reports before approving rental applications, and a destroyed credit file means rejection letters or demands for higher security deposits.
Your insurance rates can climb because some insurers use credit-based insurance scores to calculate premiums. Medical providers may refuse services or demand upfront payment. Utility companies might require deposits instead of standard billing.
Long-term costs multiply across every financial decision
If you’re forced to take out loans while your credit is trashed, you’ll pay significantly higher interest rates, adding thousands to the cost of car loans, mortgages, or personal lines of credit. The FTC’s data shows that identity theft victims spend an average of 200 hours resolving the damage, and many spend far more. The longer you wait to take action, the deeper the damage embeds itself into your financial life, making recovery exponentially harder and more expensive.
This is why the steps you take in the next section matter so much-they stop the bleeding and start the recovery process.
Steps to Take Immediately After Discovering Identity Theft
Act within hours to stop the damage
The first 24 to 48 hours after discovering identity theft determine whether you contain the damage or watch it spiral. Fraudsters move fast, and every hour you delay gives them more time to open additional accounts and rack up more debt in your name. Contact all three credit bureaus-Experian, Equifax, and TransUnion-immediately by phone or online to place a fraud alert. The alert lasts 90 days and tells lenders to verify your identity before opening new accounts, which stops most thieves cold. You’ll receive instructions to obtain copies of your credit reports, which you must review line by line for accounts you don’t recognize.
File reports with police and the FTC
File a police report the same day and obtain a copy; you’ll need this document for every creditor and bureau you contact. California law requires police to take your report, and that police report becomes your proof of identity theft when disputing fraudulent accounts. File a complaint with the Federal Trade Commission at IdentityTheft.gov, the federal resource for reporting identity theft and getting recovery guidance. The FTC creates an Identity Theft Report that carries legal weight with creditors and credit bureaus, often more powerful than a police report alone because creditors recognize it as the official federal record.
Secure your bank and credit accounts
Contact your bank and every credit card company where you have accounts, even if you don’t see fraud yet. Tell them your identity was stolen and ask them to flag your accounts for fraud. Request that they require strong authentication-passwords or PINs-for any future changes. If a debit card is compromised, close it immediately; liability is limited to $50 if you report within two business days, but escalates dramatically if you wait longer.
For bank accounts, close the old account and open a new one with a completely different account number, then change all passwords.
Document everything and dispute fraudulent accounts
Send the Federal Trade Commission Identity Theft Affidavit to each creditor’s fraud department in writing, certified mail with return receipt requested. This affidavit documents the theft and legally obligates creditors to block or correct fraudulent accounts. Keep a detailed log of every contact-dates, names, phone numbers, what was said-because you’ll reference this log for months. File disputes with the credit bureaus in writing and include your police report and ID Theft Affidavit with each submission.
Lock down your credit with a freeze
A credit freeze prevents lenders from accessing your credit file without your permission and blocks new fraudulent accounts even if the thief has your Social Security number. Freezes are free in California since 2018, take effect within three business days, and you receive a PIN to lift them temporarily when you need legitimate credit. Contact all three bureaus to place the freeze; different lenders check different bureaus, so partial freezing leaves you vulnerable. Bontrager Law helps California residents navigate this process and pursue legal action against creditors who refuse to cooperate or who continue collection efforts on fraudulent debt, ensuring you’re not held responsible for accounts you never opened.
Final Thoughts
Identity theft doesn’t end when you place a fraud alert or file a police report. The real battle begins when you fight creditors who refuse to remove fraudulent accounts, debt collectors who ignore your disputes, and credit bureaus that drag their feet correcting errors. You’ve documented everything, filed reports, and frozen your credit, but now you face months of pushing back against institutions designed to resist your claims.
A California identity theft lawyer applies legal pressure that creditors and collectors understand in ways they don’t understand phone calls from victims. When you have representation, they move faster, cooperate more readily, and stop ignoring your documentation. They know you’re serious about holding them accountable for violating California law and federal regulations that protect identity theft victims.
We at Bontrager Law represent California residents fighting back against identity theft and the financial destruction it causes. Contact us at Bontrager Law for a free consultation and let us take the fight to creditors and collectors on your behalf.