Your credit report is one of the most important financial documents you own. Lenders, landlords, and employers in California all use it to make decisions about you, and errors on that report can damage your finances for years.
At Bontrager Law, we’ve seen how credit reporting mistakes can derail people’s lives. That’s why we’ve put together these credit reporting tips for CA residents to help you monitor your report, catch errors early, and protect yourself from fraud.
Why Your Credit Report Matters More Than You Think
Your Credit Score Directly Affects Your Borrowing Costs
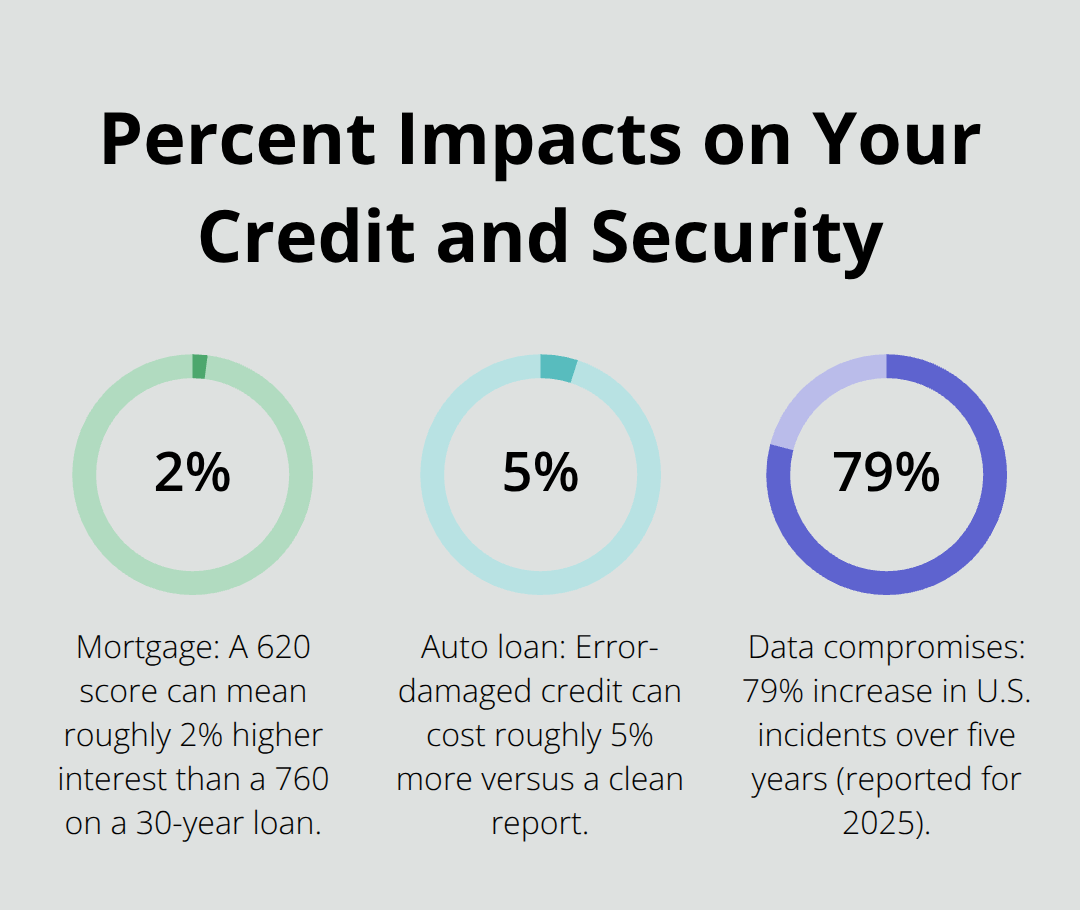
Your credit score isn’t just a number lenders look at when you apply for a mortgage or car loan. It directly impacts the interest rate you’ll pay. A person with a 620 credit score pays roughly 2% more in interest on a 30-year mortgage than someone with a 760 score, which translates to tens of thousands of dollars over the life of the loan. Banks use your credit report to calculate risk and charge higher rates to offset that risk.
The same principle applies to credit cards, auto loans, and personal loans-a lower score means higher rates across the board.
Employers and Landlords Review Your Credit Report
Beyond lenders, California employers and landlords regularly pull your credit report as part of their screening process. The FTC confirms that background checks can extend beyond credit reports to include other data that affects housing, phone service, insurance, banking, and employment decisions. Landlords use credit reports to assess whether you’ll pay rent on time. Employers in certain industries (particularly financial services, healthcare, and government positions) check credit reports to evaluate financial responsibility. If your report shows missed payments or high debt levels, you could lose out on a job opportunity or an apartment you wanted.
Errors on Your Report Carry Real Financial Consequences
A single error on your credit report can cost you thousands. A fraudulent account on your report drops your credit score immediately. Inaccurate late payments or collection accounts cause lenders to deny you for credit or charge you significantly higher rates. Someone with an error-damaged credit score pays roughly 5% more on a car loan than someone with a clean report. Over a five-year car loan, that amounts to approximately $2,000 in extra interest. California residents have strong legal protections against reporting errors, but you must take action to fix them. Inaccurate information doesn’t disappear on its own, and waiting only prolongs the damage to your finances.
Taking Control Starts With Your Credit File
Errors on your report aren’t just annoying-they actively harm your financial opportunities. The good news is that you have the power to identify and correct these mistakes. Your next step involves requesting your free credit reports from all three bureaus and reviewing them carefully for inaccuracies.
How to Get and Review Your Credit Reports
Request Your Free Reports from All Three Bureaus
Pull your free credit reports from Equifax, Experian, and TransUnion through AnnualCreditReport.com, the official government portal run by the FTC. You get one free report annually from each bureau, but current policy also offers weekly free reports, so you can check your file multiple times per year without paying. You’ll need your Social Security number, date of birth, and current address to request your reports. Pull all three reports at once rather than spacing them out-this gives you a complete picture of what’s in your file and makes it easier to spot inconsistencies between bureaus.
Why You Can’t Skip Any Bureau
Many people check only one bureau, which is a mistake. Each bureau maintains separate records, and errors on one report won’t necessarily appear on another. A creditor might report a late payment to Equifax but not to Experian, so you could miss real damage to your credit if you don’t review all three. Incomplete monitoring leaves gaps in your protection and allows errors to hide in plain sight.
Read Your Reports Line by Line
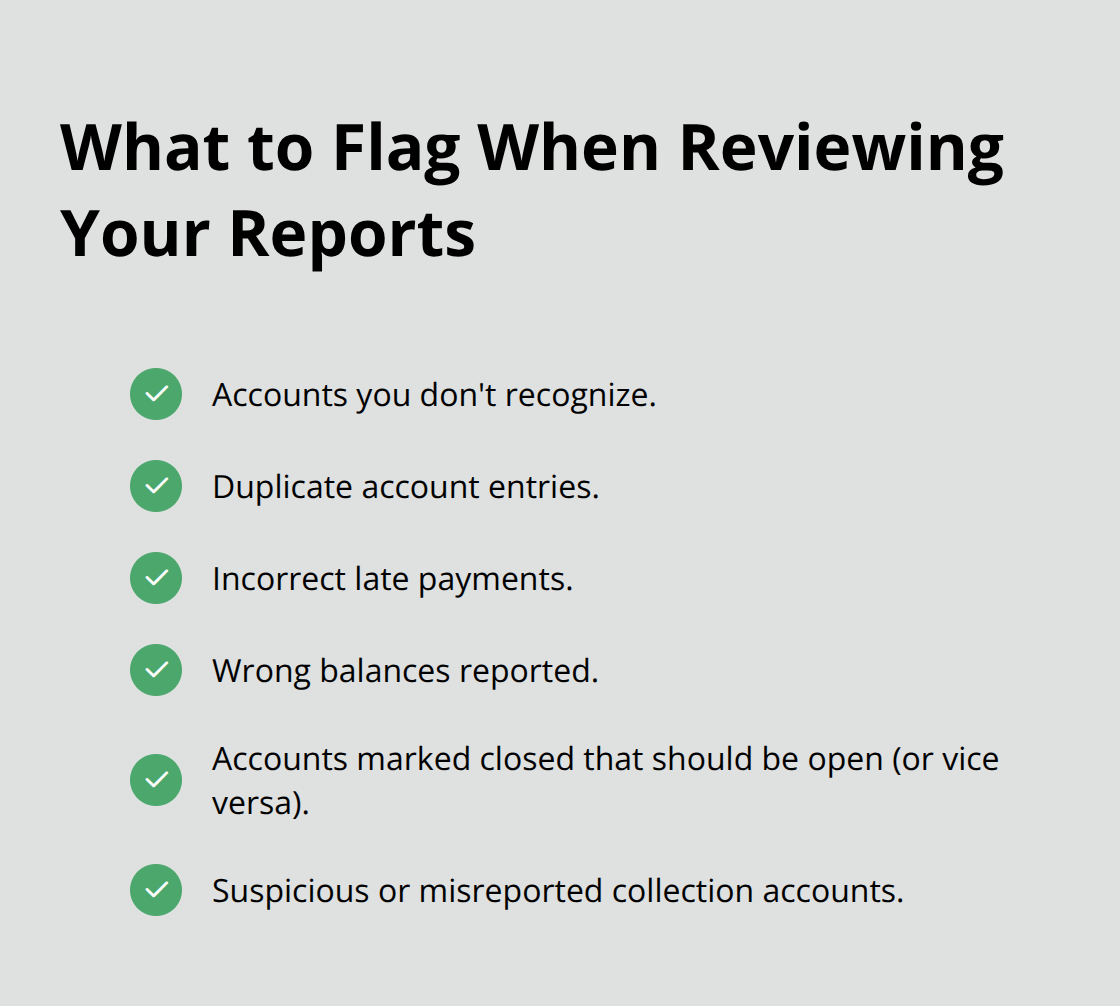
Once your reports arrive, read them carefully. Look for accounts you don’t recognize, duplicate entries, incorrect late payments, wrong balances, or accounts marked as closed when they should be open. Pay special attention to collection accounts, as these carry significant weight in credit scoring and are frequent sources of errors.
Inaccurate information stays on your report for years unless you take action-it won’t fix itself.
Dispute Errors in Writing with Documentation
When you find an error, dispute it directly with the credit bureau reporting the mistake and with the company that provided the information to that bureau (called the furnisher). The FTC provides a sample letter you can customize and send to your issuer, which documents your dispute and creates a paper trail. Include any supporting documentation-bank statements, payment receipts, or correspondence showing the account isn’t yours or the information is wrong. The bureau must investigate your dispute within 30 days and remove inaccurate information if they can’t verify it. Don’t rely on phone calls alone; send your dispute in writing to create an official record.
Know Your Rights and Next Steps
If the bureau doesn’t respond or refuses to remove the error, California law gives you strong protections. California residents have legal remedies available when credit bureaus ignore disputes or furnish false information. After filing your dispute, monitor your credit reports again in 30 to 45 days to confirm the error was removed. If it reappears, file another dispute immediately. Understanding what protections apply to you and when to escalate your case separates people who recover from reporting errors and those who remain stuck with damaged credit.
Stopping Identity Theft Before It Damages Your Credit
Your credit file is a target. The Identity Theft Resource Center reported 3,322 data compromises in the U.S. during 2025, a 79% increase over five years. California residents face particular risk because your Social Security number, address, and financial information appear on documents and in databases across the state. Once a criminal has this information, they can open credit accounts in your name, max out credit cards, or take out loans you’ll be stuck paying for. The damage happens fast, but you can block it before it starts by taking two specific actions: placing a credit freeze with the three major bureaus and monitoring your accounts regularly for unauthorized activity. A credit freeze costs nothing and stops new accounts from being opened in your name without your explicit permission. Unlike credit monitoring services that alert you after fraud occurs, a freeze prevents the fraud from happening in the first place.
Place a Credit Freeze to Block New Accounts
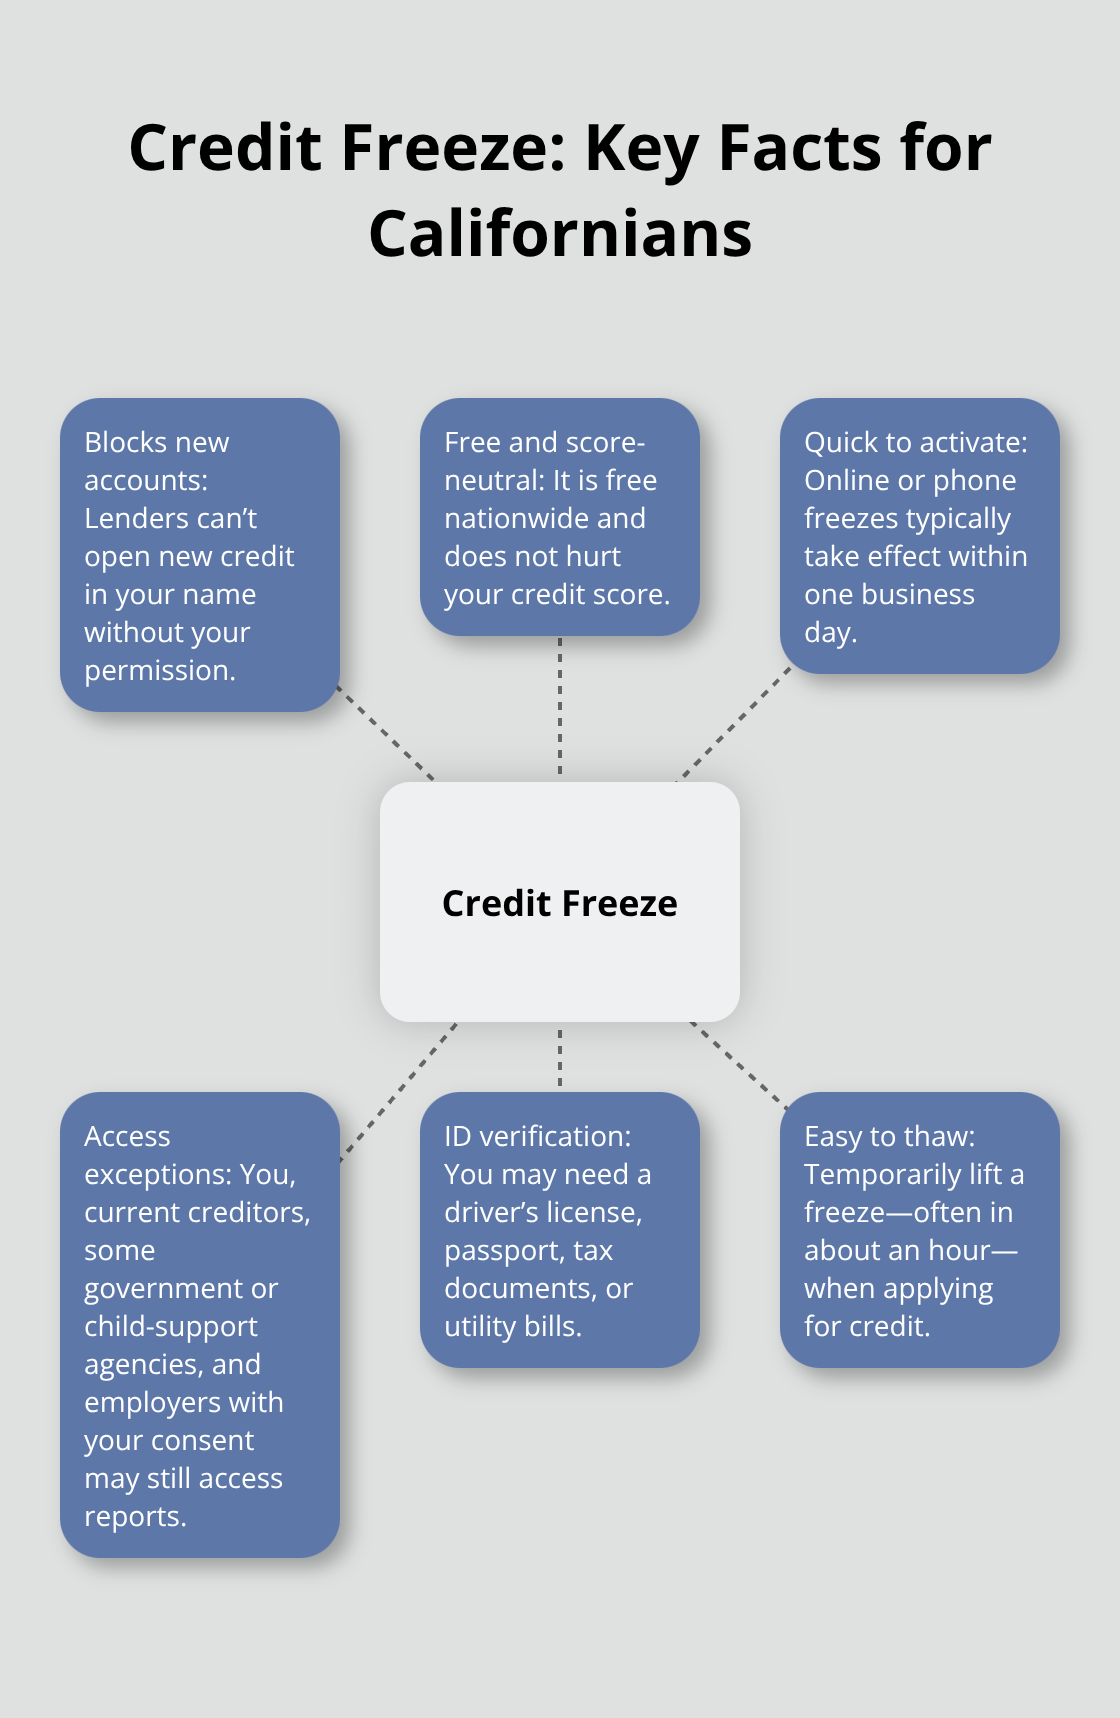
Contact Equifax at 888-378-4329, Experian at 888-397-3742, and TransUnion at 888-909-8872 to freeze your credit with all three bureaus. You can freeze online or by phone, and the freeze typically takes effect within one business day. Mail-based requests take up to three business days, so skip the mail and use phone or online options. Provide your Social Security number, date of birth, and current address. You may need additional verification like a driver’s license, passport, tax documents, or utility bills. The freeze is free nationwide and does not hurt your credit score according to CFPB guidance. When you freeze your credit, lenders cannot access your credit report to open new accounts, which blocks criminals from applying for credit in your name. The freeze blocks most people from seeing your reports, with exceptions for you, current creditors, certain government or child-support agencies, and employers with your permission.
Thaw Your Credit When You Need New Accounts
If you need to apply for a car loan, mortgage, rental, or use a buy-now-pay-later service like Affirm, you’ll thaw your credit temporarily. You can thaw online or by phone at each bureau, and the thaw takes effect in as little as one hour. After you complete your credit applications, the freeze resumes automatically or you can re-freeze manually. Plan ahead when applying for credit because you must thaw separately at each bureau, and keeping track of your freeze status prevents surprises during the application process.
Watch Your Accounts and Reports for Red Flags
Check your bank and credit card statements weekly for charges you don’t recognize. Fraud on existing accounts happens even with a freeze in place because a freeze only blocks new accounts. Criminals also commit fraud through healthcare claims, tax return theft, and other channels outside your credit file. Review your free weekly credit reports from AnnualCreditReport.com for accounts you don’t recognize, inquiries you didn’t authorize, or changes to your personal information like address or phone number.
Take Immediate Action When You Spot Fraud
If you spot fraud on an existing account, contact your bank or credit card company immediately and report the unauthorized charges. If you find a fraudulent account on your credit report that you don’t have access to, file a dispute with the credit bureau reporting it and contact the company that opened the account. Place a fraud alert with each bureau if you suspect identity theft. A fraud alert requires businesses to verify your identity before opening new accounts, adding another layer of protection on top of your freeze. California residents should contact the California Department of Financial Protection and Innovation if you experience identity theft or suspect fraud, as they offer resources and can direct you to additional protections available under state law.
Final Thoughts
Your credit report won’t fix itself, and errors stay on file for years unless you take action. Pull your free reports from all three bureaus at least once a year through AnnualCreditReport.com, or use the weekly reports now available to monitor your file more frequently. When you find an error, dispute it in writing with the credit bureau and the company that reported the information, then follow up within 30 to 45 days to confirm removal.
Protect yourself from identity theft by placing a credit freeze with Equifax, Experian, and TransUnion immediately-it costs nothing, takes one business day, and stops criminals from opening accounts in your name. Check your bank and credit card statements weekly for unauthorized charges, and review your credit reports for suspicious inquiries or accounts you didn’t create. California law provides strong protections against reporting errors and identity theft, but you must act to use them.
If a credit reporting error has already damaged your finances or identity theft has harmed you, California residents have legal remedies available. We at Bontrager Law represent individuals across California in disputes over credit reporting errors and identity theft claims against banks and large corporations. Contact us for a free case review to discuss your situation and learn how credit reporting tips CA residents can apply may help protect your rights.